Project 2030
The 2030s may test every financial plan built for the last forty years.
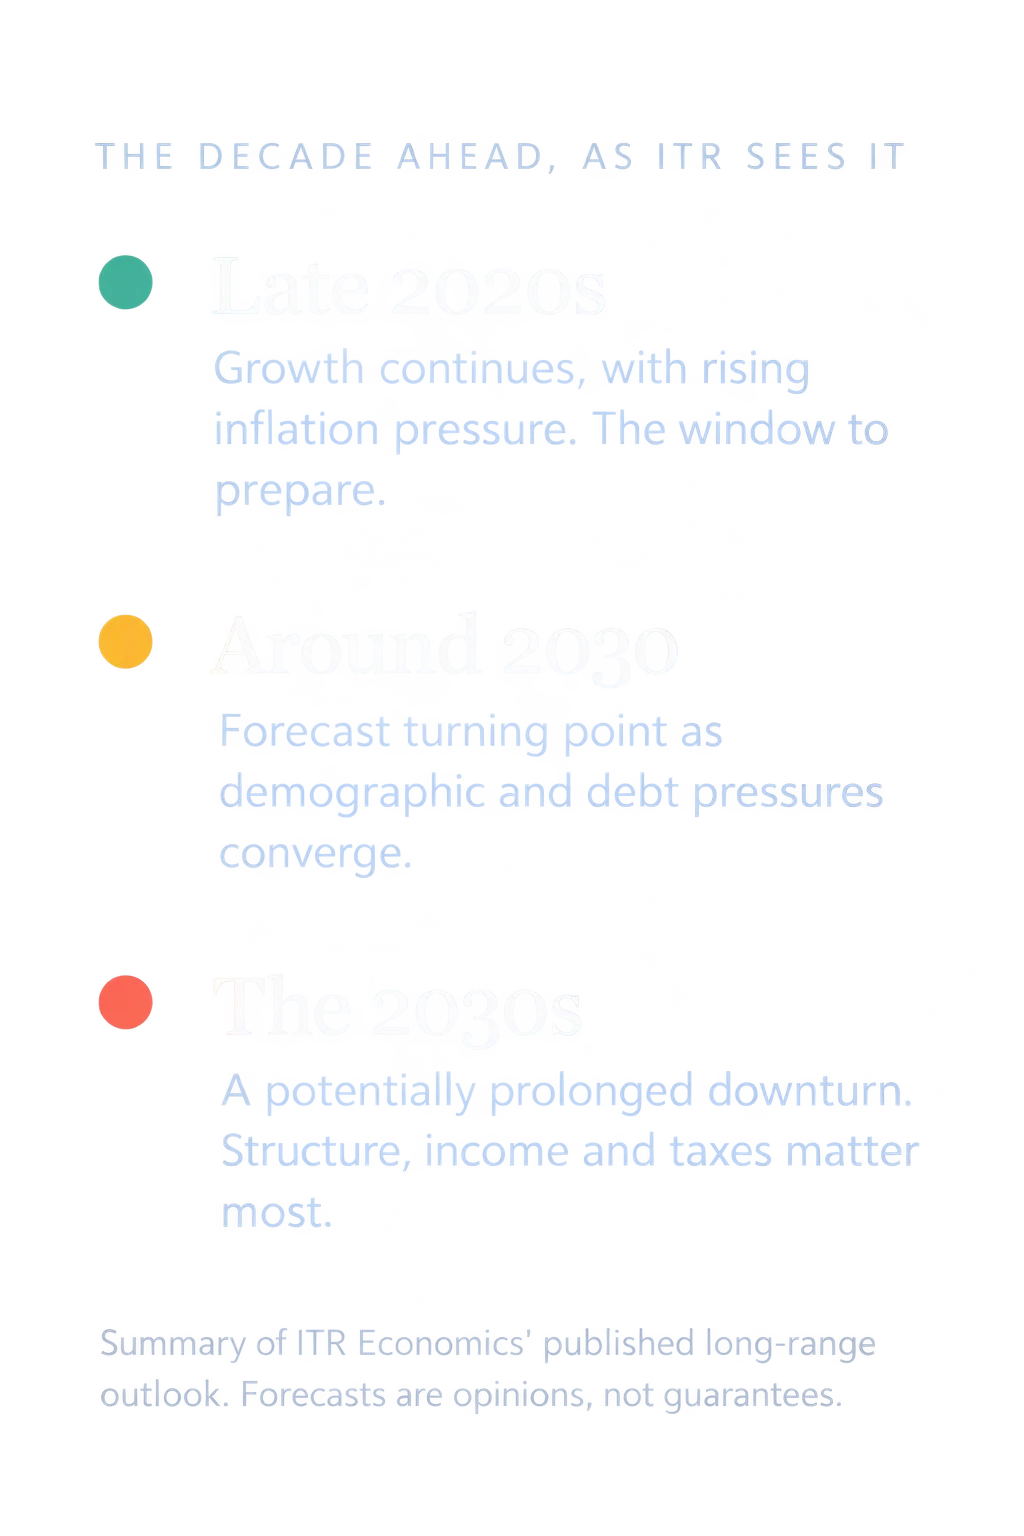
ITR Economics — an independent forecasting firm with a track record going back to 1948 — projects a severe economic downturn, potentially a depression, beginning around 2030. No forecast is certain. But the families who come through hard decades best are the ones who prepared while times were good.
LEADERSHIP & RECOGNITION
NYS Autism Spectrum Disorders Advisory Board
Charlie Massimo, Board Member
Life's WORC Honoree
December 2026
Author of two books
The Kindness Portfolio and Getting Off the Street
As featured in
[Media outlets - confirm & get compliance approval]
why the 2030s
This isn't a hunch. It's a set of slow-moving forces you can already see.
ITR's outlook rests on long-term trends rather than headlines. Each one is visible today, and together they explain why we believe planning now is prudent.
01
An aging population
Baby boomers leaving the workforce means fewer workers supporting more retirees, and less consumer spending to drive growth.
02
Entitlement pressure
Social Security and Medicare obligations grow just as the tax base that funds them narrows.
03
Rising national debt
Interest on federal debt competes with everything else in the budget, limiting the tools available in the next downturn.
04
Inflation and taxes
Persistent inflation and the likelihood of higher taxes can quietly erode purchasing power and after-tax income.
the real risk
A downturn doesn't break good portfolios. It breaks uncoordinated plans.
Most families have an investment advisor, a CPA, an attorney and an insurance agent who rarely talk to one another. In a strong economy, the gaps between them stay hidden.
In a hard decade, those gaps become expensive: selling investments at the wrong time to cover income, paying taxes that could have been avoided, estate plans written for a world that no longer exists.
That is why we act as your Personal CFO, coordinating the whole balance sheet from one seat.
HOW WE'RE GUIDING OUR CLIENTS
Six moves we're making now, while the economy is still strong.
Every family's plan is different. These are the areas we're working through with each client household ahead of the 2030s.
STRESS-TEST
Run your plan through a 2030s scenario
We model what a prolonged downturn would mean for your income, lifestyle and legacy, so decisions are made calmly today rather than in a panic later.
INCOME CERTAINTY
Secure years of income in advance
Where it fits, we lock in income at today's yields so you aren't forced to sell growth investments at the bottom of a market to pay the bills.
TAX STRATEGY
Keep more of what you earn
Roth conversions, tax-loss harvesting and smart withdrawal ordering, done while today's tax rates are known rather than waiting to see what tomorrow's will be.
DIVERSIFICATION
Look beyond the S&P 500
We're reviewing concentration risk and, where appropriate, considering high-quality bonds from fiscally stronger countries and private-market strategies that may behave differently from public stocks.
LEGACY
Protect what you're building for the next generation
We update estate plans, trusts and beneficiary designations, and address New York estate tax exposure, working directly with your attorney.
STEADY HANDS
A plan you'll stick with when it's hard
The costliest mistakes in a downturn are emotional. A clear plan, agreed on in advance, keeps your family on course when the headlines turn dark.
Coordination in practice
What a coordinated plan looks like.
Illustrative examples based on situations we commonly see. Names and details are composites, not actual clients.
The retired couple who didn't want to sell at the bottom
THE SITUATION
Recently retired, living mostly on portfolio withdrawals, and worried a long downturn would force them to sell stocks to pay the bills.
WHAT WE DID
Set aside [X] years of planned spending in high-quality income investments and coordinated withdrawal order with their CPA.
WHAT CHANGED
Their near-term income no longer depends on what the stock market does next year.
The business owner facing a New York estate tax bill
THE SITUATION
Most of the family's wealth was tied up in a business and real estate, with an estate plan written more than a decade earlier.
WHAT WE DID
Worked alongside their attorney and CPA on trusts, gifting and beneficiary updates, and planned liquidity for the next generation.
WHAT CHANGED
Projected New York estate tax exposure reduced by [approx. $X — illustrative], and one plan everyone now works from.
The widow handed five advisors' worth of paperwork
THE SITUATION
After losing her husband, she inherited accounts at several firms, outdated beneficiaries and no clear picture of her income.
WHAT WE DID
Organized everything into one view, updated beneficiaries and built a simple, reliable monthly income plan.
WHAT CHANGED
She knows what comes in each month, and one team she trusts coordinates the rest.
WHAT HAPPENS IN YOUR REVIEW
Three simple steps. No sales pitch.
A 20-minute intro call
We learn what matters to you and what you'd like the review to answer
Your 2030 stress test
We meet in Deer Park or by video and walk through how your plan would hold up in a 2030s scenario.
A written summary you keep
Your readiness findings and next steps in writing, yours whether or not you work with us.
Watch the project 2030 series
Hear it from us, in a few minutes at a time.
Short videos on what the forecast says, what it could mean for your family, and how we're helping clients prepare.
Announcement
Introduction to Project 2030
Strategy
Evidence
Preparation
The POdcast
The Kindness Portfolio
Hosted by Charlie Massimo and Peter Anastasian. Plain-spoken conversations about preparing your family for the decade ahead. Latest episode: [Episode 1 title — preparing for the 2030s].
“After thirty years, I've learned that at a certain stage of wealth, structure matters far more than returns. Get the structure right, and security follows.”
Charles Massimo
Senior Vice President, Financial Advisor · Author of The Kindness Portfolio and Getting Off the Street
WHO WE ARE
Your Personal CFO Team in
Deer Park, Long Island
Led by Charles Massimo and Peter Anastasian, our team helps affluent families, not-for-profits and women in transition coordinate investments, taxes, retirement income and estate planning in one place.
$1B+
in client assets overseen as of February 2026
30+
years guiding families through market cycles
2
books: The Kindness Portfolio and Getting Off the Street
$185B+
Wealth Enhancement
assets firm-wide
Charles Massimo
Senior Vice President, Financial Advisor
Charlie has spent more than thirty years advising families through the transitions that matter. He is the author of The Kindness Portfolio and Getting Off the Street. Charlie also serves on the New York State Autism Spectrum Disorders Advisory Board.
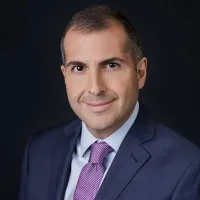
Peter Anastasian
Senior Vice President, Financial Advisor
Currently serves on Wealth Enhancement's National Advisory Leadership Council, helping bring the "Voice of the Advisor" to the firm's strategic direction. Peter has been quoted in Bloomberg, GOBankingRates and Real Assets Adviser on tax planning and navigating financial transitions.
WHO WE ARE
Frequently Asked Questions
Is the review really complimentary?
Yes. There is no cost and no obligation.
Do I have to move my accounts?
No. We review your plan where it is today. What you do with the findings is up to you.
I already have an advisor. Why talk to you?
Many people we meet do. A second look focused on the 2030s, and on how your investments, taxes and estate plan fit together, often surfaces gaps no single advisor is watching.
What should I bring?
Recent account statements, your latest tax return and, if you have one, a summary of your estate plan. We'll send a short checklist when you book.
Can we meet virtually?
Yes. We meet in our Deer Park office, by video or by phone, whichever is easiest for you.
Not ready to talk yet?
Get our free 2030 Readiness Checklist: ten questions to ask about your plan before the decade turns.
COMPLIMENTARY · NO OBLIGATION
Request your 2030 Readiness Review
A one-on-one conversation with our team about how your current plan would hold up in the decade ahead. You'll leave with:
A stress test of your income and investments against a 2030s downturn scenario
The tax opportunities worth acting on while today's rates are known
Gaps between your investments, taxes and estate plan, and who should close them
Access to our Project 2030 video series, podcast and future 2030 events
Prefer to talk now? Call 631-777-1030
Massimo-Anastasian Team
Wealth Enhancement · 724 Long Island Ave, Deer Park, NY 11729
(631) 777-1030 · [email protected] · yourpathwaystowealth.com
Economic forecasts referenced on this page are the opinions of ITR Economics, an independent third party not affiliated with Wealth Enhancement Group. Forecasts are not guarantees of future results, and actual economic conditions may differ materially. This material is for informational purposes only and is not a recommendation to buy or sell any security or an offer of any service. Investing involves risk, including possible loss of principal. Diversification does not ensure a profit or protect against loss.
Advisory services offered through Wealth Enhancement Advisory Services, LLC, a registered investment advisor and affiliate of Wealth Enhancement Group®